
On September 23, 2026, corporations around the world breathed a sigh of relief as the China-U.S. trade truce was extended by two months to January 10, 2027. Yet, while the mining industry continues to expand projects for lithium, silicon, and other minerals, one element has been subtly revolutionizing technologies and transforming power dynamics: gallium. Yes, gallium, the element that melts in your hands. Primarily used in semiconductors, it challenges the dominance of silicon and silicon carbide in the industry; the market for gallium-derived products is projected to grow from $3.7 billion in 2025 to $17 billion by 2032, a growth rate of 24.5 percent. China produces 98 percent of the world’s gallium, granting them leverage over gallium’s use in global semiconductor and defense industries.
Why do we care?
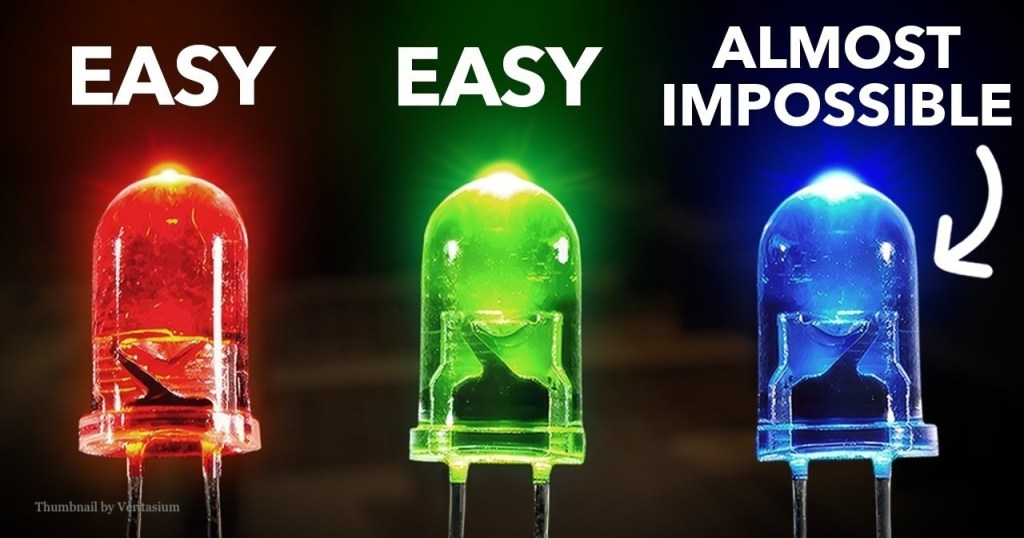
Gallium is mostly used in two forms: gallium nitride (GaN) and gallium arsenide (GaAs). GaN is very effective for high-frequency and high-power applications and is essential to fast chargers, AI chips, 5G stations, and radar. In fact, it is up to 30 percent more efficient than traditional silicon-based chargers, prompting major consumer companies like Apple to transition to gallium-based alternatives. GaN is also required for blue LEDs, a necessary component for all full-spectrum or white LED lighting. GaAs is used in fiber optics, LiDAR, and solar cells due to its high electron mobility. Together, these applications make gallium a critical mineral for innovation and national security in the fourth industrial revolution: energy is the currency of the future while high-tech weapons can be used to project power or for protection via mutually assured destruction.
Supply Chain Ramifications
Gallium is not found on its own; instead, it’s extracted as a byproduct from processing several other minerals. Ninety percent of gallium is extracted when mining aluminum, with zinc and coal mining also producing notable amounts, granting these industries control over the gallium market. Building mines takes time, so gallium production is limited both by geographical chokepoints and temporal bottlenecks. China’s effective monopoly on gallium can consequently act as leverage, particularly as the world uses increasingly more gallium for semiconductors. Gallium deposits can also be found in Japan, South Korea, and Russia, but only in marginal quantities.
International Trade Relations
Here lies the main discourse surrounding gallium. In recent years, trade relations regarding gallium have become more tenuous. The first major restrictions on gallium-based products were placed in October 2022, when the United States placed techno-nationalist restrictions on AI chip exports to China. According to the US Department of Commerce, China “seeks to become a world leader in artificial intelligence by 2030,” so the United States aims to “prevent sensitive technologies with military applications from being acquired” by restricting exports of AI chips and components, design software, and manufacturing equipment. Then, in March 2023, Japan restricted 23 types of manufacturing equipment for semiconductors to China. In response, China implemented export controls on gallium in July 2023 by verifying end-use details and licenses, due to its use in plutonium bombs.
Gallium was flowing from China to Western powers, but its products, especially advanced AI chips with 50 percent lower power losses than traditional silicon chips, were not being traded back. As Dr. Gracelin Baskaran later testified before Congress, “the consequences were predictable and swift.” China banned gallium exports to the United States in December 2024, leading to a 32 percent price increase in 2025. Only one North American company, Neo Performance Materials, recycles and produces gallium suitable for semiconductors, so the ban effectively severed the United States’ access to refined gallium. Chinese companies were largely unaffected, since the export price for Chinese gallium is almost double the price of gallium within China. The G7 condemned the ban, expressing “grave concerns regarding economic coercion, including coercion through arbitrary export restrictions that may … undermine economic security and resilience.”
These restrictions were not meant to be permanent, since China needs to import advanced AI chips as much as the United States needs gallium. “You can use [trade policy] as a bargaining chip to achieve reciprocity or level the playing field,” asserts trade economics expert Douglas Irwin. Thus, a one-year trade truce was struck on November 9, 2025: China would allow companies to obtain gallium importing licenses, while the United States would lower tariffs on China and lift the ban of exporting US technologies such as semiconductor manufacturing equipment. This agreement demonstrates that, despite their fierce competition, the United States and China are interdependent. Even still, the process of obtaining gallium licenses remains difficult, as both nations attempt to retain leverage.
The Future of Gallium
Predictable consequences such as rising prices and geopolitical tensions have raised the alarm about the need to collectively invest in primary gallium production. The US government allocated US$36 million in total in fall of 2025 for research and development in gallium extraction and recycling. Additionally, international partnerships have been crucial to expanding gallium production. In partnership with US-based Indium Corp, Rio Tinto has conducted initial extraction tests in Quebec and believes they could produce up to 40 metric tons per year, accounting for five to ten percent of global production. The European Investment Bank has financed 90 million euros to Metlen for gallium extraction in Greece. Finally, Alcoa aims to produce 100 metric tons of gallium per year in West Australia beginning in late 2026, backed by the Japanese, American, and Australian governments. These strategic investments substantiate the importance of gallium for emerging technologies such as AI, and ultimately drive new technological breakthroughs.




You must be logged in to post a comment.